Ask my AI Legal Analyst about fintech compliance?
Tap a question for an instant, free answer (no email needed), or describe your money-movement model and the analyst routes you to the right next step. Attorney-supervised AI, not legal advice.
Common questions, always free
Do I need a money transmitter license??
Six questions, thirty seconds. I score your MTL exposure live as you answer, flag the specific triggers I would investigate first, and point you to the right next step. Attorney-supervised heuristic, not legal advice.
Where do customer funds land first??
Pick the description that fits your actual money flow, not what you tell customers.
How long do you hold the funds??
Any user-visible balance is a bigger flag than transit time.
What does your product do with the money??
Pick the closest primary use. You can note secondary use cases in the analysis.
Are you the principal, or the agent of a licensed party??
This is the exemption most fintechs try to lean on. It only works if the paper matches reality.
Which U.S. states do you serve??
More states = more analysis, and higher odds a difficult jurisdiction is in the mix.
Does your product touch crypto or digital assets??
Crypto adds a second layer of state-specific rules on top of standard MTL.
Fintech compliance packages
Most fintech compliance starts with one of two questions: do I need an MTL, and is my KYC program defensible. These packages answer both.
Money Transmitter Analysis
Federal analysis plus a 50-state + D.C. regulatory survey identifying potential money-transmitter licensing triggers and prioritizing jurisdictions for further action or local-counsel confirmation where required.
- Federal definition analysis (BSA, FinCEN guidance)
- State-by-state regulatory survey identifying potential MTL triggers across 50 states + D.C.
- Agent-of-payee vs principal payment analysis
- Bank-partnership / sponsor-bank model analysis
- Stablecoin / crypto-MTL implications if applicable
- Ranked state-licensing roadmap with cost estimates
- Written memo, board-ready
KYC / AML Program Review
Written review of your existing KYC and AML program against applicable BSA, FinCEN, and OFAC requirements and guidance, with a prioritized gap and remediation memo.
- Customer Identification Program (CIP) review
- Customer Due Diligence (CDD) and EDD program audit
- Sanctions (OFAC) screening process review
- Suspicious Activity Report (SAR) filing posture
- Recordkeeping and BSA reporting compliance check
- Written gap memo with prioritized remediation list
Payments Contract Stack
Coordinated written payments package for fintechs and payments-active SaaS, covering customer payment terms, processor or sponsor-bank agreement markup, dispute and chargeback protocol, and reserve or hold provisions.
- Customer payments terms tailored to your model
- Processor / sponsor-bank agreement markup template
- Chargeback and dispute protocol
- Reserve / hold language with state-law sensitivity
- Reg E / Reg Z disclosures where applicable
- Coordinated defined terms across all documents
Who this is for, and who it isn't
This is for you if:
- Fintech founders pre-launch through Series B
- SaaS companies adding payments or money-movement features
- Bank-partner / banking-as-a-service operators
- Crypto-adjacent companies needing MTL clarity
- Companies hitting first state-regulator inquiry letters
This isn't for you if:
- Federally chartered banks (outside this page's standard scope)
- Investment advisors registered under the Advisers Act
- Securities-token offerings (use Securities Startup Counsel Hub)
- BSA enforcement / DOJ investigation defense (outside my practice scope)
My approach
Fintech compliance is risk-mapping at scale: 50 states, federal regulators, and bank partners. Get the map drawn before you ship.
Structured intake
No call or meeting is required.
Tap for detail ↻Structured intake
Structured written intake: I review your money flow, customer profile, fund custody, bank-partner relationships, target jurisdictions, and current licensing or compliance posture from the written intake and documents you provide. No call or meeting is required.
Tap to flip back ↻I run the analysis
I deliver your ordered package as a written, board-ready work product.
Tap for detail ↻I run the analysis
Delivery: the KYC / AML Program Review and Payments Contract Stack are delivered within two business days after the signed engagement, payment, complete materials, and conflicts clearance. The Money Transmitter Analysis follows the delivery timing stated in the written engagement because its 50-state + D.C. regulatory survey is non-routine.
Tap to flip back ↻Execute the roadmap
You or the compliance professionals or counsel you select handle licensing applications and operational implementation.
Tap for detail ↻Execute the roadmap
Implementation: You or the compliance professionals or counsel you select handle licensing applications and operational implementation. I can answer written follow-up questions within the agreed scope; additional work is separately scoped. I do not provide regulator appearances or enforcement representation.
Tap to flip back ↻Recent client results
"Sergei’s MTL roadmap saved us from a six-figure compliance retrofit. We chose a sponsor-bank model instead of state-licensing in 23 states."Fintech CEO · saved $200K+ in licensing costs
"KYC review found three SAR-trigger workflows that weren’t documented. Closed before our state regulator inquiry."Bank-partner SaaS founder
"Payments contract stack came back coordinated and consistent. Our processor signed without redlining the customer-side terms."Embedded-finance founder
Why work with me
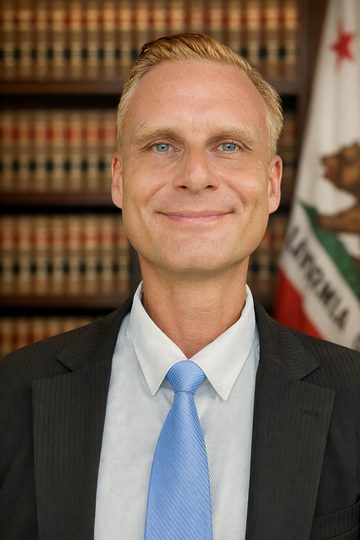
Sergei Tokmakov, Esq.
I have been a California-licensed business attorney since 2011. My practice includes written analysis and drafting involving payments, fintech regulatory issues, KYC/AML programs, and related commercial contracts.
The packages are flat-fee. You know what the analysis costs before it starts, which matters in fintech, where compliance work can otherwise be a black-hole hourly engagement.
Frequently asked questions
Do I need an MTL if I’m using a sponsor bank?
Often no. The agent-of-payee or sponsor-bank model can keep you out of MTL territory in many states. But not all. The MTL analysis package maps state-by-state whether your specific structure triggers licensing.
What’s the difference between KYC and CDD?
KYC (Know Your Customer) is the umbrella term. CIP (Customer Identification Program) is the specific BSA-required process for verifying customer identity. CDD (Customer Due Diligence) is the ongoing risk-rating and monitoring layer. The KYC review covers all three.
Do you handle MTL applications themselves?
I provide the written analysis and licensing roadmap. The package does not include preparation or filing of money-transmitter license applications. You or counsel or compliance professionals you select handle the applications. I do not operate a referral service. With your authorization, I can provide my written work product to counsel you independently retain.
What about BSA/AML examination support?
I can provide written analysis of an initial state or FinCEN inquiry through an agreed written scope. If additional written work falls outside an existing flat-fee scope, $300/hour may be used only as overflow under a written engagement. I do not provide agency appearances, examination representation, or enforcement defense.
Do you handle Reg E or Reg Z disclosures?
Yes. The Payments Contract Stack package includes Reg E (consumer EFT) and Reg Z (TILA / open-end credit) disclosures where applicable to your product.
What about crypto / stablecoin MTL?
The Money Transmitter Analysis can identify potential crypto and stablecoin regulatory triggers, including New York BitLicense and California DFPI issues. The nationwide component is a regulatory survey and issue-spotting roadmap, not a state-specific legal opinion in jurisdictions where I am not admitted. State-specific conclusions or filings may require counsel licensed in that jurisdiction.
Related resources I've written
Securities Startup Counsel
For raise-side legal work and securities posture.
SaaS Legal Package
For SaaS-only documents (non-fintech).
Stripe Frozen Funds Lawyer
When a payment processor holds your business funds.
Contract Review
Single-document review starting at $1,000.
Fractional CLO
Ongoing fintech legal work across compliance, contracts, and governance.
Map the fintech compliance landscape before you ship.
MTL analysis $3,500. KYC/AML review $2,500. Payments contract stack $3,000. Pick the one that matches the question you’re trying to answer.